The Pradhan Mantri Vidyalaxmi (PM-Vidyalaxmi) Scheme is a Government of India initiative designed to help students finance higher education through collateral-free and guarantor-free education loans at designated Quality Higher Educational Institutions (QHEIs). The scheme also provides interest support to eligible students from families with lower incomes.
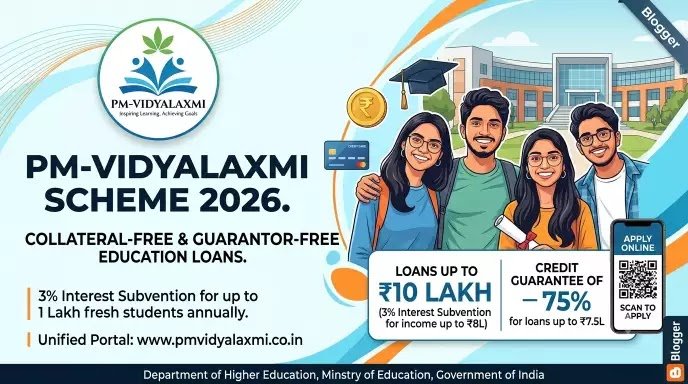
Approved by the Union Cabinet on 6 November 2024, the scheme aims to reduce financial barriers to higher education. Students admitted on merit to eligible institutions can apply for an education loan regardless of their family income. Additional interest support is available to qualifying applicants subject to the scheme’s eligibility rules and annual limits.
According to the Government of India’s July 2026 information, the scheme covers 1,425 designated institutions. Students can apply through the official PM-Vidyalaxmi portal, which also provides application tracking and grievance support. Official scheme portal (PIB).
Table of Contents
PM-Vidyalaxmi Scheme 2026: Overview
| Particulars | Details |
|---|---|
| Scheme name | Pradhan Mantri Vidyalaxmi Scheme |
| Common name | PM-Vidyalaxmi |
| Launched/approved | 6 November 2024 |
| Implementing ministry | Ministry of Education, Government of India |
| Main objective | Improve access to higher education through education loans. |
| Loan type | Collateral-free and guarantor-free, subject to scheme and bank rules |
| Eligible institutions | Designated Quality Higher Educational Institutions (QHEIs) |
| Family income limit for education loans | No income ceiling for the loan itself |
| Interest support | 3% during the moratorium period for eligible students with family income up to ₹8 lakh |
| Additional interest support | Full interest subvention may be available under PM-USP CSIS for eligible students with family income up to ₹4.5 lakh. |
| Government credit guarantee | 75% for eligible loans up to ₹7.5 lakh |
| Repayment period | Up to 15 years, excluding the moratorium period |
| Application mode | Online |
| Official website | pmvidyalaxmi.co.in |
| Helpline | 1800 1031 |
The education loan and the interest subsidy are separate benefits. Approval for a loan does not automatically guarantee an interest subsidy.
What Is the PM-Vidyalaxmi Scheme 2026?
PM-Vidyalaxmi is a central-sector scheme that helps eligible students access education finance for degree and diploma programmes at designated higher educational institutions in India.
The scheme is intended to make education financing more accessible by allowing eligible students to apply for loans without providing collateral or a third-party guarantor under the special loan product. The loan amount depends on the institution’s fees and other eligible education-related expenses.
The scheme has two major components:
- Education loan: Eligible students admitted on merit to designated institutions can apply for a collateral-free and guarantor-free education loan, subject to the bank’s assessment and applicable rules.
- Interest subvention: Eligible students meeting the relevant family-income conditions may receive government support towards interest during the course period and the one-year moratorium that follows.
The scheme also provides a government-backed credit guarantee to participating lenders for eligible loans up to ₹7.5 lakh. This guarantee supports the lending institution; it does not mean the student is exempt from repaying the loan. (PM-Vidyalaxmi guidelines)
Benefits of the PM-Vidyalaxmi Scheme 2026
1. Collateral-free education loans
Students admitted on merit to eligible institutions can apply without providing property or other collateral under the scheme’s special loan product. A third-party guarantor is also not required under the scheme, subject to the applicable conditions.
2. No family-income ceiling for the education loan
Students from all family-income groups may apply for an eligible education loan. However, family income matters when determining eligibility for interest subvention.
3. Support for education-related expenses
The loan can cover eligible costs associated with the course, including:
- Tuition fees.
- Hostel and mess charges.
- Other institutional fees.
- Reasonable living expenses during the course.
- A reasonable-quality laptop and other eligible education-related expenses.
The bank determines the approved loan amount based on eligible expenses, institutional charges and applicable lending rules.
4. Interest subsidy for eligible families
Students with annual family income up to ₹8 lakh may qualify for 3% interest subvention on the eligible loan amount up to ₹10 lakh during the moratorium period. The benefit is subject to the scheme’s conditions and annual beneficiary limit.
5. Government credit guarantee
The government provides a 75% credit guarantee for eligible education loans up to ₹7.5 lakh. This is a guarantee to support lenders, not a grant or loan waiver for students.
6. Digital application and tracking
Students can apply through the PM-Vidyalaxmi portal, select participating banks, monitor application progress and use the grievance mechanism where necessary. (Official scheme portal, PIB)
PM-Vidyalaxmi Scheme 2026: Eligibility Criteria
Applicants should check the following conditions before submitting an application.
Educational eligibility
- The student must secure admission on merit to a designated quality higher educational institution in India.
- The course must be an eligible degree or diploma programme at the institution.
- The admission must satisfy the scheme’s rules.
- Admission through management quota, NRI quota or similar categories is not eligible for the scheme benefit.
PM-Vidyalaxmi Scheme 2026: Family income eligibility
| Benefit | Family-income condition |
|---|---|
| Apply for the PM-Vidyalaxmi education loan. | No income ceiling for the loan itself |
| 3% interest subvention under PM-Vidyalaxmi | Annual family income up to ₹8 lakh, subject to conditions |
| Full interest subvention under PM-USP CSIS | Annual family income up to ₹4.5 lakh, subject to CSIS conditions |
Students should not confuse eligibility for an education loan with eligibility for interest subsidy. A student may qualify for a loan but not qualify for interest subvention.
PM-Vidyalaxmi Scheme 2026: Institution eligibility
The student must be admitted to an institution included in the designated QHEI list. The list includes eligible public and private institutions selected under the scheme’s criteria, including specified NIRF rankings and categories of government institutions.
Important: Do not assume that every college or university is covered. Search for the institution on the official PM-Vidyalaxmi portal before applying. (PIB scheme backgrounder)
PM-Vidyalaxmi Interest Subsidy Explained
Interest subvention means that the government pays an eligible portion of the interest on behalf of the student during the specified period. It is not a waiver of the entire education loan.
1. PM-Vidyalaxmi: 3% interest subvention
Students with annual family income up to ₹8 lakh may qualify for 3% interest subvention on education loans up to ₹10 lakh during the moratorium period.
The moratorium period generally covers the course duration plus one year. The subsidy is subject to the scheme’s eligibility criteria and is limited to up to one lakh fresh students each year.
If the loan exceeds ₹10 lakh, the interest-subvention benefit is calculated only on the eligible portion, as specified by the scheme.
2. PM-USP Central Sector Interest Subsidy Scheme (CSIS)
Eligible students from families with annual income up to ₹4.5 lakh may qualify for full interest subvention during the moratorium period on education loans up to ₹10 lakh under PM-USP CSIS. The scheme has its own course, institution and other eligibility requirements.
PM-Vidyalaxmi and CSIS are related but distinct schemes. Students should check which benefit applies to their circumstances.
3. Can a student receive another government scholarship and interest subsidy?
Students already receiving another Central or State Government scholarship, another education-loan interest-subvention benefit or fee reimbursement may be ineligible for interest-subvention benefits under the relevant scheme rules. Check the official guidelines before selecting the interest-subsidy option. (Official PM-Vidyalaxmi FAQs, PIB)
Documents Required for PM-Vidyalaxmi Scheme
The exact documents depend on the loan application, bank and any interest-subsidy claim. Students should prepare the following where applicable:
- Aadhaar and other accepted identity documents.
- Student photograph.
- Parent or guardian details and photograph, if requested.
- Admission letter or proof of admission.
- College or university fee structure.
- Class 10 and Class 12 certificates and marksheets, as applicable.
- Previous qualifying examination marksheets.
- Income certificate or other acceptable proof of annual family income when claiming interest subvention.
- Bank account details and any documents requested by the participating lender.
- Course-related expense details and supporting documents.
- Category or other supporting certificates, if applicable.
The official portal’s FAQs describe document upload requirements and specify acceptable formats. Follow the current portal instructions rather than relying on a generic checklist alone. (PM-Vidyalaxmi FAQs)
How to Apply for the PM-Vidyalaxmi Scheme Online
Students can apply through the official digital portal.
- Visit pmvidyalaxmi.co.in.
- Register as a student using the details requested by the portal.
- Log in to your account.
- Complete the common education-loan application form.
- Enter your personal, academic, institution and course details accurately.
- Search for and select your eligible college or university.
- Choose participating banks as permitted by the portal.
- Upload the requested documents.
- If eligible, select the option to seek interest subvention and provide the required income documentation.
- Review the application and submit it.
- Save the application reference number and track the status online.
- Respond promptly if the bank requests additional information or documents.
The portal facilitates applications, but the participating bank assesses and decides the education loan under the applicable lending rules. Students should monitor their application and contact the bank if additional steps are required. (Official portal, official FAQs)
PM-Vidyalaxmi Scheme: Loan Amount and Repayment
There is no fixed maximum loan amount imposed by the scheme for the education loan itself. The approved amount depends on eligible course fees and associated expenses, the institution and the bank’s assessment.
The scheme guidelines state that the repayment period can extend up to 15 years, excluding the moratorium period. The moratorium generally covers the course duration plus one year.
Interest rates vary by participating bank. Under the scheme guidelines, the rate is capped at the bank’s Externally Benchmarked Lending Rate (EBLR) plus 0.5%. Participating banks may offer an additional interest concession under applicable conditions.
Before accepting a loan, students should review the sanction letter, interest rate, repayment schedule, any applicable insurance costs and the total amount payable. (PM-Vidyalaxmi scheme guidelines, PIB)
PM-Vidyalaxmi Scheme 2026: How to Check Whether Your College Is Eligible
Before applying, confirm that your college or university is included in the designated institution list.
- Visit the PM-Vidyalaxmi portal.
- Open the institution search or designated QHEI list.
- Enter the institution’s name and select the relevant state and district, where prompted.
- Check the exact name in the results.
- Confirm that your admission category and course meet the scheme conditions.
If the institution does not appear, contact the institution’s administration or the official scheme helpdesk for clarification. Do not assume eligibility solely because the college is well known or accredited.
PM-Vidyalaxmi Scheme 2026: Current Interest-Subvention Claim Notice
The official PM-Vidyalaxmi portal currently displays an important notice stating that the interest-subvention claim submission window for financial year 2025–26 is open from 1 September 2026 to 31 December 2026.
Students who applied for an education loan through the PM-Vidyalaxmi portal should confirm that they selected the interest-subvention option and contact their financing bank or branch to ensure that an eligible claim is submitted within the specified window.
This notice concerns the submission of eligible claims for the stated financial year; it does not mean every student automatically qualifies. Check the portal for current instructions and eligibility conditions. (Official portal notice)
Frequently Asked Questions (FAQs)
1. What is the PM-Vidyalaxmi Scheme?
It is a Government of India scheme that helps eligible students admitted to designated higher educational institutions obtain collateral-free and guarantor-free education loans, with additional interest support for qualifying students.
2. Who can apply for PM-Vidyalaxmi?
Students admitted on merit to designated Quality Higher Educational Institutions in India can apply for an education loan, subject to the scheme and bank rules. Interest-subsidy benefits have separate income and eligibility conditions.
3. Is there an income limit for the education loan?
There is no family-income ceiling for applying for the education loan itself. Family income is relevant when determining eligibility for interest subvention.
4. How much interest subsidy is available?
Eligible students with annual family income up to ₹8 lakh may receive 3% interest subvention on eligible education loans up to ₹10 lakh during the moratorium period. Other eligible students may qualify for full interest subvention under PM-USP CSIS, subject to its separate conditions.
5. Is the loan completely free?
No. It is an education loan that must be repaid. The scheme offers collateral-free and guarantor-free lending under specified conditions and may provide interest support to eligible students.
6. Can students admitted through management quota apply?
Admissions through management quota, NRI quota or similar categories are not eligible for the scheme benefit.
7. How can I apply?
Apply through the official PM-Vidyalaxmi portal, complete the common application form, provide the required documents and follow the participating bank’s instructions.
8. Does the government pay the full education loan?
No. The scheme does not automatically pay the entire education loan. The student remains responsible for repayment, while the government provides defined interest support to eligible beneficiaries and a credit guarantee to participating lenders under specified conditions.
9. What is the helpline number?
The official PM-Vidyalaxmi portal lists the toll-free helpline as 1800 1031. Check the portal for current support information.
Conclusion
The Pradhan Mantri Vidyalaxmi Scheme can help eligible students access higher education through collateral-free and guarantor-free education loans at designated institutions. Students from families with annual income up to ₹8 lakh may also qualify for 3% interest subvention, while certain students with family income up to ₹4.5 lakh may qualify for full interest support under PM-USP CSIS.
Before applying, verify your institution’s eligibility, read the loan conditions, prepare the necessary documents and check whether you qualify for interest subsidy. Use only the official PM-Vidyalaxmi portal for the application and follow-up.
Rohanshi Mhatre aims to bridge the gap between government initiatives and citizens by delivering clear, reliable, and easy-to-follow information so that everyone can take advantage of available schemes.